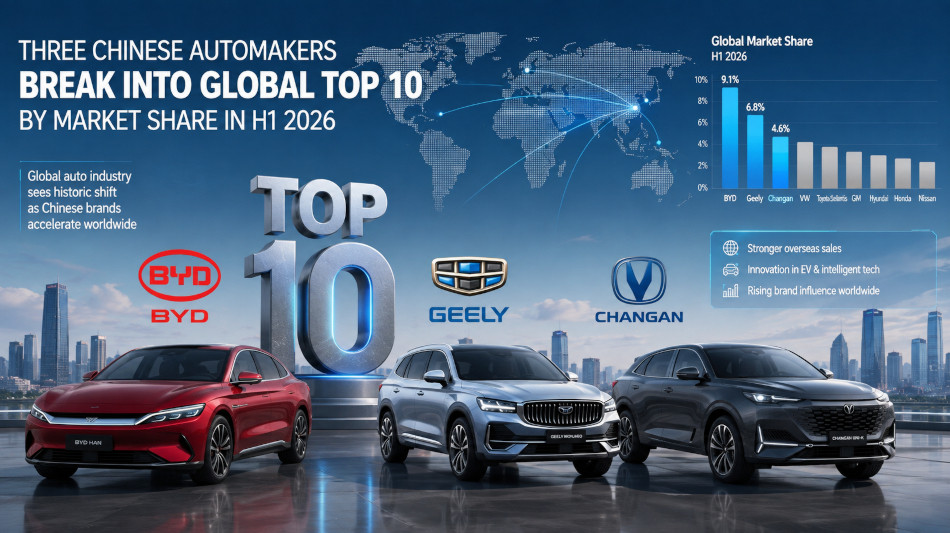
Three Chinese carmakers enter the global automotive top 10

For decades, the upper reaches of the global motor industry changed slowly. Toyota, Volkswagen, General Motors, Ford and the large European and Asian alliances traded places, but the basic hierarchy remained familiar. The first half of 2026 has broken that pattern. BYD, Geely and Chery all entered the world’s ten largest automotive groups by market share at the same time, turning what had once been described as a future threat into a present commercial reality.
Toyota retained first place with 11 per cent of the global market, followed by Volkswagen with 8.1 per cent and Hyundai-Kia with 7.6 per cent. The established order has therefore not collapsed. Yet the centre of gravity has shifted unmistakably. BYD ranked sixth with 4.8 per cent, Geely seventh with 4.6 per cent, while Chery reached joint ninth alongside Ford with 4.1 per cent. Together, the three Chinese groups controlled 13.5 per cent of worldwide vehicle sales during the period.
This is not merely another strong half-year for China. It is evidence that Chinese manufacturers are becoming permanent members of the global automotive establishment.
A decade compressed into one market cycle
The speed of the change is more revealing than the ranking itself. In 2016, BYD held only 0.6 per cent of the global market, Geely 1.5 per cent and Chery 0.8 per cent. Their combined share was 2.9 per cent. Ten years later, it had risen by 10.6 percentage points to 13.5 per cent, almost five times the earlier level.
The comparison requires some care. Global rankings often combine groups, alliances and controlled brands rather than measuring individual badges. Geely’s figure includes a broad portfolio extending beyond the Geely name to companies such as Volvo Cars, Polestar, smart, Lotus and Proton. Hyundai and Kia are grouped together, as are Renault and Nissan. Even so, the methodological caveat does not weaken the central conclusion. Chinese capital, engineering, platforms and supply chains now support a much larger share of the vehicles bought around the world.
Nor is the advance limited to three companies. SAIC stood just outside the top ten in eleventh place with 3.7 per cent. Changan and Great Wall Motor occupied seventeenth and eighteenth place. This depth matters. China is no longer relying on one exceptional champion. It has developed a crowded field of manufacturers capable of competing across electric cars, plug-in hybrids, conventional vehicles, commercial models and increasingly premium segments.
Exports have become the decisive engine
The most striking feature of the first half was that the international advance occurred while China’s domestic passenger-car market was contracting sharply. Retail sales in the home market fell by roughly one fifth, forcing manufacturers to search more aggressively for growth abroad. At the same time, China exported about 5.1 million vehicles during the first six months, an increase of more than 65 per cent. Exports of new-energy vehicles exceeded 2.35 million and more than doubled.
That divergence explains much of the new global ranking. Chinese manufacturers are no longer expanding internationally simply because their home market is enormous. They are doing so because overseas sales have become essential to factory utilisation, revenue growth and competitive survival. A difficult domestic environment, marked by intense price competition and falling demand for combustion-engined cars, is accelerating the industry’s globalisation.
The result is a shift from opportunistic exporting to the construction of multinational operations. Cars are still being shipped from Chinese ports in record numbers, but the leading groups are also building regional research centres, parts networks, assembly operations and full production plants. Their ambition is no longer to sell a few competitively priced models abroad. It is to create durable local businesses.
BYD rises globally while confronting pressure at home
BYD’s sixth-place ranking is the clearest symbol of the transformation. A decade ago, the company was still widely regarded outside China as a battery producer that also made cars. It has since built one of the industry’s most integrated manufacturing systems, covering batteries, semiconductors, electric motors, power electronics and complete vehicles.
During the first half of 2026, BYD sold about 1.81 million new-energy vehicles worldwide. Overseas passenger-car and pick-up sales approached 790,000, rising by roughly 68 per cent from a year earlier. International markets therefore supplied much of the company’s momentum while domestic volumes remained under severe pressure.
There is an important qualification. BYD’s global market share of 4.8 per cent was lower than its 5.4 per cent share in 2025. Its arrival in sixth place should not be mistaken for uninterrupted expansion. The company is navigating a demanding product transition, intense Chinese competition and the costs of building sales and service operations across multiple continents.
Its response has been to broaden the business geographically and technologically. Battery-electric cars remain central, but plug-in hybrids give BYD access to markets where charging infrastructure is incomplete or consumers remain cautious about fully electric vehicles. Local production in Brazil and planned manufacturing capacity in Europe are intended to reduce logistics costs, improve political acceptance and limit exposure to import barriers. The advantage of vertical integration remains formidable, but it must now be matched by dealer quality, residual values, after-sales service and sustained profitability.
Geely’s strength lies in its portfolio
Geely’s rise to seventh place reflects a different model. Rather than depending on one dominant marque, the group has assembled a network of brands, technologies and international assets. Its scale is partly the result of acquisitions and partnerships, but increasingly also of shared electric architectures, software, hybrid systems, purchasing and research.
Geely Auto, the listed core of the wider holding group, sold more than 1.42 million vehicles in the first half of 2026. Overseas sales reached about 474,000, an increase of 158 per cent, while overseas new-energy vehicle sales rose to more than 277,000. The figures show that Geely’s international growth is no longer being carried mainly by conventional export models. Electrified vehicles are becoming the centre of its expansion. The broader group structure gives Geely several advantages. It can serve mass-market, premium and luxury customers through different brands, spread development costs across common platforms and draw upon engineering centres in China and Europe. It has expanded its parts distribution network, added local manufacturing in markets such as Brazil and Indonesia, and is deepening its European presence. The planned manufacturing partnership with Ford in Spain is especially revealing: a Chinese group that once sought credibility through foreign technology is now being approached as a partner for competitive electric and low-emission vehicles.
Complexity is also Geely’s risk. A large brand portfolio can create duplication, internal competition and an expensive management structure. Its continuing consolidation under the One Geely strategy is therefore as important as its sales growth. The group must prove that scale and technological breadth can produce consistent margins rather than merely impressive volumes.
Chery turns export expertise into global scale
Chery’s ninth-place position may be the least surprising to industry observers, even if it is less familiar to many consumers in Western Europe. The company has spent more than two decades building export channels, often entering developing and middle-income markets well before other Chinese manufacturers.
That long preparation is now visible in the numbers. Chery sold more than 1.35 million vehicles in the first half of 2026, up 7.7 per cent. Exports reached almost 944,000, an increase of 71.5 per cent, meaning that close to seven out of every ten vehicles were sold outside China. New-energy vehicle sales rose to more than 475,000. Chery’s international strategy is becoming more sophisticated. The company is moving beyond shipments from China towards local engineering, compliance, supply-chain management and manufacturing. Its European operations centre and research institute in Barcelona are intended to adapt products and operations to regional requirements. Cooperation with EBRO has revived production at the former Nissan site in Barcelona and created a platform for deeper European localisation.
The company passed 20 million cumulative global sales in July, but scale alone will not determine whether its top-ten position endures. Chery operates through several brands and must build clear identities for them, maintain quality across rapidly expanding production and provide reliable service in markets where its dealer network is still young. Export leadership creates reach; lasting consumer confidence requires institutions that take longer to build.
The competitive response is already changing
The rise of BYD, Geely and Chery is altering the decisions of established manufacturers. The initial response to Chinese competition centred on tariffs, investigations and warnings about industrial overcapacity. Those measures remain significant. The European Union continues to apply additional duties to battery-electric cars made in China, including rates of 17 per cent for BYD and 18.8 per cent for Geely.
Trade protection, however, is only one part of the response. Traditional manufacturers are increasingly seeking Chinese partners for electric platforms, software, batteries, development speed and lower-cost production. Ford’s planned cooperation with Geely in Spain and General Motors’ renewed long-term partnership with SAIC illustrate a more complicated reality. The established groups remain competitors, but they also need access to capabilities developed inside China. This does not mean that Chinese companies have already won the global automotive contest. Toyota, Volkswagen and Hyundai-Kia retain far greater scale, mature financing operations, extensive service networks and deeply established brands. They also possess manufacturing footprints that are already local in most major markets. Those advantages cannot be replicated quickly.
What has changed is the basis of competition. Product development cycles are shorter, software and driver-assistance systems influence purchasing decisions, and battery cost has become as important as engine expertise once was. Chinese manufacturers have built their strongest positions precisely in these areas. Their domestic market forced them to launch models quickly, integrate digital features across lower price bands and compete in an exceptionally severe pricing environment.
The next test is permanence, not entry
A place in the global top ten is a milestone, not a guarantee. High sales can conceal weak margins. Rapid overseas expansion can strain working capital, dealer standards and spare-parts supply. Local regulators are paying closer attention to subsidies, cybersecurity, data handling and the resilience of battery supply chains. Consumers will judge new brands not only by showroom technology and purchase price, but also by reliability, insurance costs, resale values and the availability of repairs years after a model is launched.
Political resistance will also intensify as Chinese companies capture more market share. Local production can soften that resistance by creating jobs and tax revenue, yet it also raises costs and reduces some of the manufacturing advantage enjoyed in China. The companies that remain in the top ten will be those that learn to operate as genuinely local manufacturers in multiple regions rather than as exporters with overseas sales offices.
The early figures for the second half suggest that the first-half ranking was not an isolated event. In July, BYD’s overseas passenger-car and pick-up sales approached 180,000. Geely Auto exceeded 100,000 overseas sales for a second consecutive month, while Chery’s monthly exports passed 200,000 for the first time. International demand is no longer a secondary contribution to these companies. It is becoming the central pillar of their growth.
The global motor industry has therefore entered a new phase. The question is no longer whether Chinese manufacturers can reach the world’s leading tier. Three of them are already there. The more consequential question is which companies can convert extraordinary export momentum into trusted brands, profitable local operations and a durable place at the top of the automotive hierarchy.
O.Peters