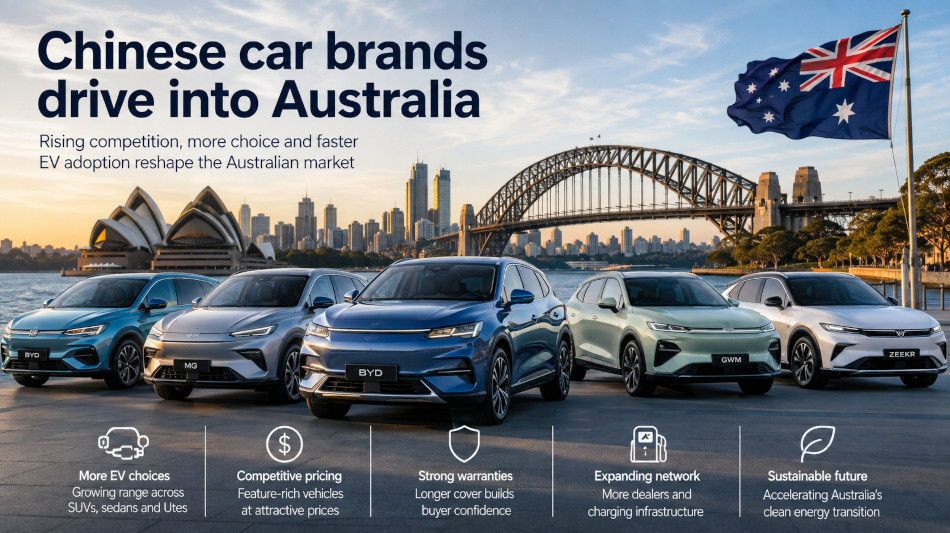
Chinese car brands reshape Australia’s automotive market

Australia’s new-car market has crossed a decisive threshold. Chinese manufacturers are no longer peripheral challengers attempting to win over a limited group of price-conscious motorists. They have become one of the principal forces shaping vehicle prices, equipment levels, electrification and consumer expectations across the country.
The latest registration figures illustrate the scale of the change. More than 38,000 vehicles built in China were delivered in Australia during July 2026, almost twice as many as a year earlier and substantially more than the number sourced from Japan. Four Chinese brands finished among the country’s ten largest automotive marques for the month, while another narrowly missed the leading group. BYD took second place behind Toyota, ahead of manufacturers that have spent decades building recognition in Australia. Chery, GWM and MG also entered the top ten, while Geely finished immediately behind them. Omoda Jaecoo and Zeekr recorded sales volumes that would have seemed improbable for recently established brands only a short time ago.
This is no longer a temporary sales surge driven by a handful of discounted electric cars. It is a structural reordering of one of the world’s most open and competitive automotive markets.
From low-cost outsiders to mainstream competitors
The first wave of Chinese vehicles sold in Australia was largely defined by price. Early products attracted motorists willing to compromise on refinement, brand familiarity or resale certainty in return for a lower purchase cost. That reputation has not disappeared entirely, but it no longer reflects the breadth or technical maturity of the market.
MG and GWM helped normalise Chinese ownership by building substantial sales volumes, expanding their dealer networks and moving beyond entry-level products. BYD subsequently accelerated the transition by offering electric vehicles and plug-in hybrids that combined competitive pricing with contemporary interiors, long equipment lists and increasingly credible driving ranges.
They have since been joined by Chery, Omoda Jaecoo, Geely, Zeekr, Leapmotor, XPeng, Deepal, GAC, Denza and several commercial-vehicle specialists. The result is a product range extending from compact urban electric cars to family SUVs, dual-cab utility vehicles, off-road models, luxury people movers and high-performance premium vehicles.
Chinese manufacturers are therefore no longer competing in a single corner of the market. They are contesting nearly every important segment, often with several models from related brands positioned at different price levels. The distinction between a Chinese brand and a Chinese-built vehicle is also becoming less meaningful. Some familiar Western and Asian marques source vehicles from Chinese factories, use Chinese-developed electric platforms or rely on batteries and electronic systems produced by Chinese suppliers. Australian versions of several internationally recognised electric vehicles are already manufactured in China.
Vehicle origin has consequently become more complex than the badge attached to the bonnet.
BYD defines the speed of the transformation
No company demonstrates the pace of change more clearly than BYD. The manufacturer entered the Australian passenger-vehicle market in 2022 and has developed from a relatively unfamiliar electric-car supplier into one of the country’s largest automotive brands. BYD delivered 7,857 vehicles in July 2026, an increase of more than 70 per cent compared with the same month a year earlier. Only Toyota sold more vehicles. During the exceptional end-of-financial-year market in June, BYD came within 243 deliveries of overtaking the long-standing market leader.
The BYD Sealion 7 electric SUV was the fourth most popular individual vehicle in Australia during July, with 2,548 deliveries. It finished ahead of numerous established petrol, diesel and hybrid models and continued to challenge the Tesla Model Y in one of the country’s most commercially important segments. The company’s strength lies in the breadth of its electrified range. Compact cars, saloons, medium and large SUVs, plug-in hybrids and the Shark 6 utility vehicle allow BYD to reach customers with very different transport requirements. Its premium Denza division is simultaneously moving into territory traditionally occupied by European luxury brands and high-end Japanese four-wheel drives.
Control over battery development, electric drivetrains and much of the underlying supply chain gives BYD considerable flexibility. It can introduce models quickly, adjust specifications and compete aggressively on price without relying entirely on external technology providers. The next test will be less about attracting first-time customers and more about retaining them. Sustained success will depend on service capacity, parts availability, repair times, software support and the quality of the ownership experience long after the initial sale.
The challenge extends far beyond one manufacturer
BYD may be the most visible example, but the broader competitive pressure comes from the number and variety of Chinese companies now operating in Australia. Chery delivered more than 4,600 vehicles in July, supported by the popularity of the Tiggo 4. The compact SUV became one of the country’s strongest-selling vehicles and demonstrated that Chinese growth is not confined to fully electric models.
GWM continues to compete through a wide portfolio covering conventional petrol vehicles, hybrids, plug-in hybrids, electric cars, utility vehicles and serious four-wheel drives. Its Haval, Tank, Ora and Cannon products enable the company to address family, recreational and commercial buyers without depending on a single technology. MG remains a significant mainstream presence, particularly among motorists seeking affordable hatchbacks and SUVs. Its Chinese ownership is now well established, although the badge retains the familiarity of its British origins. The brand’s challenge is to preserve its value positioning whilst improving consistency, refinement and long-term customer confidence.
Geely has rapidly gained ground through the EX5 electric SUV, which recorded more than 2,000 deliveries in July. Zeekr, the group’s premium electric marque, achieved almost 1,900 deliveries with the 7X during the same month. Those figures show that Chinese manufacturers can now compete above the budget end of the market, including against Tesla and established European premium brands.
Omoda Jaecoo is following a similar strategy by combining distinctive styling, extensive equipment and aggressive pricing. XPeng is emphasising software and digital technology, while Denza and Zeekr are attempting to prove that Chinese manufacturers can establish credible premium identities rather than relying solely on lower prices. The term Chinese car therefore describes a national industry, not a single product philosophy. Its manufacturers are competing against one another almost as intensely as they are competing with Japanese, Korean, European and American rivals.
Electrification provides the accelerator
The rapid expansion of electric and plug-in hybrid sales has created especially favourable conditions for Chinese manufacturers. Australians purchased 23,510 battery-electric vehicles in July 2026, representing more than 22 per cent of the market. A further 10,359 plug-in hybrids were delivered. Together, the two categories accounted for 33,869 vehicles and more than 32 per cent of all sales.
Across the first seven months of the year, electric vehicles and plug-in hybrids secured almost 27 per cent of the new-vehicle market, more than twice their share during the corresponding period of 2025.
Chinese companies do not control the entire transition, but they are particularly well positioned to benefit from it. Years of investment in battery production, electric platforms, power electronics, software and high-volume manufacturing have enabled them to offer electrified vehicles across a wider range of prices. The leading electric models in July reflected that advantage. Alongside the Chinese-built Tesla Model Y, the BYD Sealion 7, Geely EX5 and Zeekr 7X were among Australia’s most popular battery-powered vehicles.
Plug-in hybrids have also become an important part of the strategy. They offer electric operation for shorter journeys whilst retaining a combustion engine for long-distance travel. That combination has particular appeal in a geographically large country where public charging coverage remains uneven and many motorists regularly travel beyond metropolitan areas. The technology delivers its strongest benefits when owners charge regularly. A plug-in hybrid driven mainly on its combustion engine can lose much of its economic and environmental advantage, especially when the vehicle is heavier than an equivalent conventional model.
Australia’s New Vehicle Efficiency Standard is likely to reinforce the transition. Suppliers have been required to meet fleet-average carbon dioxide targets since July 2025. Manufacturers with extensive electric, plug-in hybrid and efficient hybrid ranges are consequently well placed to comply, while brands dominated by higher-emission vehicles face growing pressure to adjust their product mix.
Value has become the industry’s new baseline
Competitive pricing remains central to the success of Chinese brands, but the definition of value has expanded. Motorists are not merely being offered less expensive vehicles. Many Chinese models include large digital displays, surround-view cameras, connected services, panoramic roofs, heated and ventilated seats, comprehensive driver-assistance systems and extensive convenience equipment at prices previously associated with more basic specifications.
This has recalibrated expectations across the market. Features that were once reserved for expensive variants are increasingly regarded as standard equipment. Established manufacturers must respond either by lowering prices, increasing specification or providing a clearly superior ownership proposition. The pressure is particularly visible in the electric market, where Chinese brands have helped reduce the entry cost and introduced more competition in the crucial small and medium SUV categories.
A low purchase price does not, however, guarantee low total ownership costs. Insurance premiums, servicing schedules, tyre prices, finance charges, energy consumption and depreciation can materially alter the financial calculation. Electric vehicles may reduce energy and routine maintenance expenditure, but heavier models can require costly tyres, while collision repairs involving sensors, cameras and battery structures may affect insurance costs.
Frequent price reductions can also influence resale values. A buyer who receives a substantial discount benefits immediately, but an owner who purchased the same model earlier may see the used value fall more quickly. This is not unique to Chinese manufacturers, although rapid model cycles and aggressive pricing can make the effect more pronounced.
Consumers should therefore compare the entire ownership package rather than concentrating exclusively on the advertised drive-away price.
Safety must be judged model by model
The assumption that Chinese vehicles are inherently unsafe is increasingly contradicted by independent testing. Several high-volume models have achieved five-star safety ratings under demanding current assessment protocols. The BYD Sealion 7 and Geely EX5 are among the electric SUVs that have secured top ratings, while models from MG, GWM and Chery have also performed strongly in crash protection and active-safety assessments.
Modern Chinese vehicles commonly include autonomous emergency braking, blind-spot monitoring, lane-support technology, rear cross-traffic assistance and multiple airbags. In some cases, this equipment is standard across the range rather than restricted to more expensive variants.
A five-star result should nevertheless be checked for the exact model, production date and powertrain. Ratings can apply only to particular variants, and a model name may cover vehicles with different safety specifications.
The operation of driver-assistance systems also varies. Lane-keeping functions, speed warnings and driver-monitoring technology can feel intrusive or poorly calibrated even when they contribute to a strong laboratory assessment. A thorough test drive remains essential. Country of origin should not be treated as either a guarantee of safety or a reason for rejection. The relevant questions concern the individual vehicle, its verified rating, its standard equipment and the quality of its real-world behaviour.
The real contest begins after the sale
The greatest uncertainty surrounding newer brands is no longer whether they can produce appealing vehicles. It is whether they can support those vehicles across Australia for many years. A generous warranty is valuable only when the manufacturer has an effective dealer and service network, trained technicians, diagnostic equipment and a reliable parts supply. Owners in regional and remote areas should pay particular attention to the distance to an authorised repairer and the availability of alternative servicing arrangements.
Software support is also becoming part of the ownership equation. Modern vehicles depend heavily on operating systems, mobile applications, digital keys, charging controls and over-the-air updates. Manufacturers must demonstrate that these systems will remain secure, functional and supported throughout the vehicle’s working life. Residual values are another unresolved factor. Established marques benefit from decades of sales history, fleet demand and recognised used-car values. Newer entrants have less long-term data, making depreciation more difficult to predict. Strong sales may ultimately support used demand, but rapid replacement cycles and frequent discounting can create uncertainty.
Insurance should be investigated before purchase rather than afterwards. Premiums and repair conditions can differ considerably between models, particularly where replacement components or specialist repairs are involved. These considerations do not make a newer Chinese vehicle a poor choice. They simply mean that the strength of the local operation matters as much as the specifications of the car.
Established manufacturers remain formidable
The rise of Chinese brands does not mean that Japanese, Korean, European and American manufacturers are disappearing from Australia. Toyota remains the clear market leader and continues to benefit from an extensive dealer network, strong residual values and deep customer loyalty. Kia, Hyundai, Mazda, Ford, Mitsubishi, Subaru and other established companies retain considerable advantages in servicing coverage, brand recognition and accumulated reliability data. Their challenge is that those advantages can no longer justify an unlimited price premium.
Their response is already changing the market. More electrified vehicles are reaching Australia, specifications are becoming richer and product-development partnerships increasingly involve Chinese manufacturers, suppliers and factories. Several familiar marques now use China-developed electric platforms or manufacture selected models in China for export.
Chinese automotive technology is therefore influencing the Australian market even when the finished vehicle carries a non-Chinese badge.
Competition is also forcing traditional manufacturers to reconsider development cycles. Chinese companies can move from concept to production at exceptional speed, updating cabins, software and powertrains far more frequently than the conventional seven-year model cycle once allowed. Speed alone does not guarantee quality, but it places pressure on slower organisations to respond more rapidly to changing consumer preferences.
Expansion will eventually be followed by consolidation
Australia cannot sustain an unlimited number of brands, distributors and overlapping models. Some newer entrants will build sufficient volume to justify permanent dealer networks and local investment. Others may struggle to establish recognition or differentiate themselves in an increasingly crowded field. The likely winners will not necessarily be those offering the lowest initial price. They will be the companies that combine competitive vehicles with dependable servicing, stable management, transparent warranties, strong parts supply and convincing resale performance.
BYD, GWM, MG and Chery have already achieved the scale required to be treated as established market participants. Geely, Zeekr, Omoda Jaecoo and several other newer brands are now attempting to build the same level of permanence at a far faster pace. For Australian motorists, the immediate effect is greater choice, stronger price competition and quicker access to new electric and hybrid technology. The longer-term effect will be a fundamental change in how vehicle brands are judged.
Chinese cars are no longer an emerging category at the edge of the Australian market. They are now a central part of it. The remaining question is not whether Australian buyers will accept them, but which manufacturers will earn their confidence for the decade ahead.
M.Brown