RYCEF
0.4000

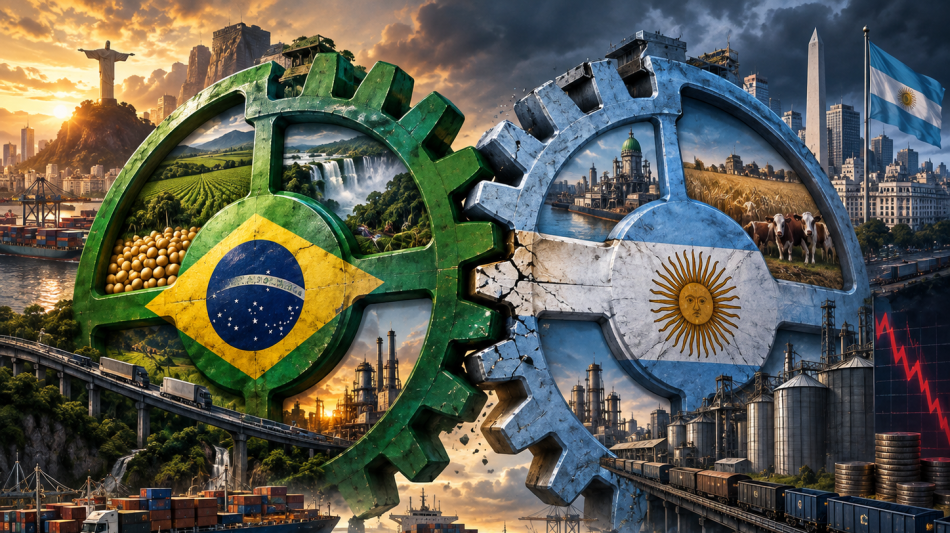
Brazil did not start the world’s newest trade fights. But it may be the clearest beneficiary of them. As tariffs and counter-tariffs rewire supply chains, the global economy is rediscovering a simple truth: when the two largest powers punch each other in the face, the countries that can reliably ship what both sides still need—food, fuel, minerals, and industrial inputs—suddenly gain leverage. In 2026, Brazil sits unusually well-positioned at that crossroads: big enough to matter, diversified enough to pivot, and politically non-aligned enough to sell to almost everyone.
The result is a windfall that is not limited to one commodity, one destination, or one trade route. It is an accumulating advantage—built from agricultural dominance, commodity depth, expanding logistics, and a diplomatic posture that often keeps doors open even when superpowers slam theirs shut.
The mechanics of a “winner” in a trade war
Trade wars rarely “create” demand. They redirect it. When access to a supplier becomes expensive, politically risky, or simply uncertain, buyers don’t stop consuming overnight—they scramble for alternatives. The winners are not necessarily the lowest-cost producers on paper, but those that can scale, deliver consistently, and absorb sudden shifts without breaking contracts or bottlenecking ports.
Brazil checks those boxes across multiple categories:
- Food and feed: soybeans, corn, meats, sugar, coffee, orange juice, and a rising list of processed foods.
- Industrial commodities: iron ore and other mining outputs central to construction, steelmaking, and heavy industry.
- Energy and energy-linked products: crude, refined fuels, and biofuels—plus the agricultural inputs that can substitute for constrained supplies elsewhere.
In practice, this means Brazil benefits in two distinct ways. First, it captures market share when buyers avoid politically “hot” suppliers. Second, it gains bargaining power on price and contract terms as buyers compete for reliable volumes.
The soybean pivot: the clearest example of redirected trade
Few products illustrate the trade-war reshuffle better than soybeans. Soy is not just a food item. It is a strategic input into animal protein, cooking oils, and industrial uses. When tariff retaliation hits agriculture, it hits one of the most politically sensitive sectors in any country—farmers—and it hits fast.
In periods of heightened U.S.-China tariff friction, Chinese import demand has repeatedly surged toward Brazil. That shift is not merely a one-off substitution; it can become a structural change if buyers invest in new supply relationships, shipping routines, and processing infrastructure built around Brazilian origin.
Once that happens, regaining lost market share becomes difficult even if tariffs later ease. Traders and processors begin to treat the alternative supply line not as a temporary workaround, but as a baseline.
Brazil’s advantage here is scale. It can supply massive volumes at competitive costs, and it can expand output over time. Even when weather shocks disrupt harvests, global buyers often still prefer Brazilian origin because the system around it—ports, traders, processors, shipping lanes—has grown used to handling huge flows.
Beyond soy: meat, poultry, and the “protein flywheel”
Agricultural redirection does not stop at the farm gate. It cascades downstream. When soybean meal becomes abundant and competitively priced, livestock producers can scale. When livestock scales, exports of beef and poultry can rise. When those exports rise, investment flows into cold-chain logistics, feed efficiency, genetics, and processing capacity—further improving competitiveness.
This creates a “protein flywheel”: feed drives meat; meat exports justify processing; processing boosts value capture; value capture funds technology and expansion. In a trade-war environment, this flywheel spins faster because importers prioritize resilience over marginal price differences.
A quiet shift: from raw supplier to value-added exporter
For decades, Brazil’s critics argued that the country was “stuck” exporting raw materials. The trade-war era complicates that narrative.
When supply chains fragment, buyers do not just look for raw inputs. They look for reliable intermediate products: processed foods, refined or semi-processed materials, standardized industrial components, and contract-manufactured outputs that can bypass politically sensitive origins.
Brazil has been steadily moving in that direction. Its agribusiness sector, in particular, has expanded processing capacity—crushing soy into meal and oil, scaling meatpacking and poultry processing, and pushing branded and semi-branded exports into more markets.
This matters because processed exports typically deliver higher margins, more stable employment, and deeper industrial ecosystems than raw commodity exports. A trade war can act like an accelerant: it rewards producers that can deliver not only bulk volume, but also predictable specifications, traceability, and year-round fulfillment.
Playing both sides—without becoming a proxy
Brazil’s strategic value in a trade war is not only what it sells, but whom it can sell to. Many countries are forced into binary choices—pick a bloc, pick a standards regime, pick a political camp. Brazil has, so far, avoided being locked into a single side. It trades deeply with China, maintains significant economic ties with the United States, and keeps commercial channels with Europe and large emerging markets.
That flexibility is itself a commercial asset. If one destination becomes less attractive—because of tariffs, quotas, sanctions risk, or demand weakness—Brazil can often redirect to another without reinventing its entire export model.
This is where the country’s sheer economic breadth becomes decisive. Brazil is not a niche exporter of one resource; it is a multi-commodity, multi-destination supplier with long-established trading relationships. That makes it harder to isolate—and easier to integrate into whatever “re-globalized” world replaces the old one.
Tariffs on Brazil can still leave Brazil ahead
It sounds contradictory: how can a country be a “winner” if it is also hit by tariffs? Because relative advantage matters more than absolute pain. If tariffs are applied broadly across many countries, Brazil can still win by being less penalized than competitors—or by benefiting elsewhere from the same tariff regime. Even when Brazil faces targeted duties, the damage depends on how exposed the economy is to the affected market, how easily exporters can pivot, and how many products are exempted or rerouted.
In recent tariff episodes, Brazil’s exposure has often been manageable because:
- the economy is large and diversified,
- exports to any single partner represent only part of total output,
- and trade diversion toward other large markets can offset part of the hit
In some scenarios, tariffs even create second-order opportunities: if manufacturers move away from one contested geography, they look for politically safer production bases, raw inputs, and alternative routes. Brazil’s market size, resources, and expanding industrial clusters make it a candidate for that reallocation—especially in resource-linked manufacturing.
The critical minerals angle: a new chapter in leverage
Trade wars are no longer only about steel, washing machines, or soybeans. They increasingly revolve around the upstream ingredients of modern industry: critical minerals, processing capacity, and the ability to secure supply chains for strategic technologies.
Brazil has meaningful reserves in several mineral categories and, crucially, has begun emphasizing the step that matters most: processing and refining, not just digging things out of the ground. In a world where major powers worry about overdependence on any single processing hub, a resource-rich country that can credibly build refining capacity becomes more than a commodity exporter. It becomes a strategic partner.
This is a slower-moving advantage than soybeans. Mines and refineries are not built in a season. But the direction is clear: trade conflict is pushing countries to treat supply chains as national-security infrastructure. Brazil, with scale and geological variety, has an opening to become a cornerstone of “de-risked” supply networks—if it can execute.
Energy and geopolitics: cheap inputs, tricky politics
Trade wars overlap with sanctions and energy politics, and Brazil has navigated that overlap with a pragmatic streak. In an era of volatile fuel markets, discounted supply offers can lower costs domestically and improve export competitiveness indirectly—because cheaper energy reduces production and logistics costs across the economy. But bargains can come with political risk if suppliers are under sanction pressure or if new restrictions emerge.
Brazil’s challenge is to preserve its image as a reliable, rules-respecting trade partner while still protecting domestic economic interests. That balancing act is not unique to Brazil, but it is higher-stakes for a country trying to maximize trade-war gains without triggering punitive responses.
Why the momentum is real—and why it is fragile
Brazil’s trade-war boom is not an accident. It is a product of structural strengths that the country has spent decades building, even if imperfectly: agricultural technology, large-scale production, export infrastructure, and a commercial diplomacy that generally seeks options rather than ultimatums. But the boom is also fragile, for three reasons.
1) Infrastructure is still the bottleneck.
Brazil can grow more soy, raise more cattle, and mine more ore—but if roads, rail, ports, and storage cannot keep up, the advantage erodes into delays and higher costs. Global buyers reward reliability; a single season of congestion can push them to diversify elsewhere.
2) Environmental constraints are tightening.
The world is not only watching prices. It is watching land use, deforestation, and traceability. Markets and regulators increasingly demand proof of compliance. Brazil’s export future depends on whether it can scale production while convincingly controlling illegal deforestation and improving transparency across supply chains. Without that, access to premium markets can narrow.
3) Trade wars shift quickly—and can turn inward.
A country can benefit from diversion today and be targeted tomorrow. If Brazil’s gains become politically salient abroad—especially in election cycles—calls for countermeasures can rise. The “winner” label can paint a target.
The bigger picture: Brazil as a stability premium
Ultimately, Brazil’s biggest advantage in a fractured global economy may be intangible: it sells stability. Not perfection—Brazil remains a complex, high-variance country with fiscal pressures, political noise, and real governance challenges. But compared with flashpoint suppliers, it offers something increasingly scarce: the ability to ship essential goods at scale while maintaining working relationships across rival blocs.
In a world where trade is becoming a tool of statecraft, that ability is worth a premium. And that is why Brazil can emerge as the big winner of the trade war—not because it avoids the fallout, but because it is structurally built to capture the rerouting, the repricing, and the reinvestment that follow when global trade stops being “efficient” and starts being “strategic.”